The Architecture of Capital Distribution
A budget is not a gentle wishlist of what a company hopes to achieve, but a ruthless mathematical contract proving what it must execute.
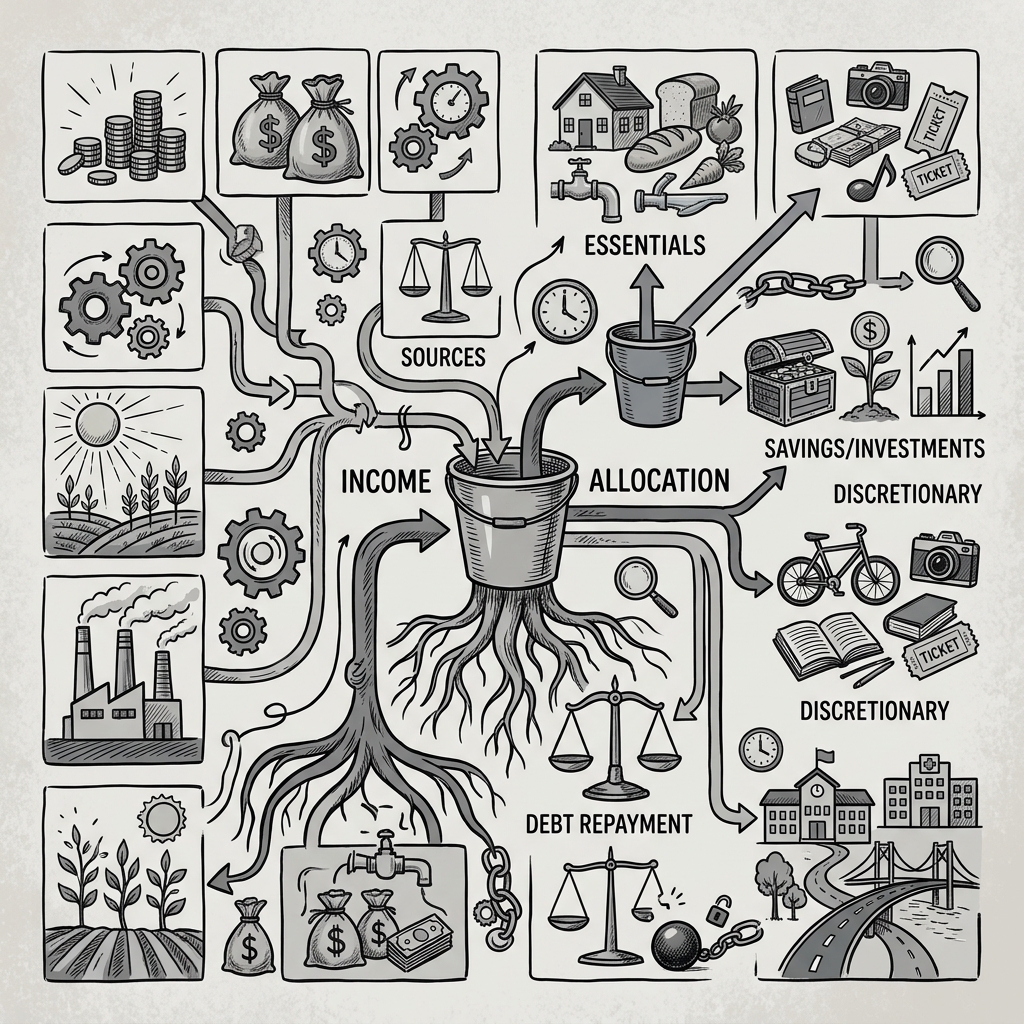
No matter how flawless a corporate strategy looks on brilliant screens in a boardroom, it remains merely an illusion unless the exact financial resources are allocated to support it. Strategic Resource Allocation and Budgeting represent the process of distributing limited corporate capital with millimeter precision to serve the organization's ultimate objectives. Companies do not possess infinite money or time; therefore, every single financial decision means sacrificing another opportunity.
The Needs of the Field and the Farmer's Strategy
To comprehend this complex mechanism, imagine a farmer who must distribute a highly limited supply of seeds and water across a massive field. Certain patches of this field are barren and dry, while other plots are exceptionally fertile and bathed in sunlight.
- Poor Management: If the farmer distributes the water equally across every corner of the field, the barren soil simply absorbs the precious water without yielding anything. Meanwhile, the fertile soil fails to reach its true potential because it was starved of the extra water it desperately needed. Consequently, the harvest is poor, and the entire village faces starvation in winter.
- Strategic Management: A master farmer, instead of pouring capital into barren dirt, focuses the limited water exclusively on the fertile regions that guarantee the best yield. If necessary, they completely abandon the unproductive areas and divert all resources into a single strong point to ensure a massive harvest. Budgeting is precisely this art of pouring corporate water onto the right soil.
Incremental Budgeting and the Trap of Laziness
When setting budgets, most traditional corporations rely on Incremental Budgeting. Under this system, managers simply take their total expenditures from the previous year, add a small percentage for inflation, and demand that amount for the new year.
- This approach is akin to the farmer blindly declaring, "We poured one bucket of water here last year, let's pour a bucket and a half this year," without ever inspecting the soil.
- The expenses of outdated, inefficient projects or departments that no longer serve the company continue indefinitely. "Zombie expenses" inflate the corporate structure, breeding sluggishness and bureaucracy.
Zero-Based Budgeting (ZBB)
In stark contrast, the most successful and agile enterprises employ Zero-Based Budgeting (ZBB). In this system, the past is entirely irrelevant. At the dawn of every new financial year, the budget spreadsheet starts at an absolute "zero."
- Regardless of what was spent last year, every department manager must mathematically prove exactly how every single penny they request will serve the overarching corporate strategy.
- Returning to our metaphor; the farmer stands with a bucket of water every morning and asks each plot of land, "Why do you deserve this water today? What kind of harvest will you give me?"
- Any project or unit lacking a solid, strategic justification receives zero funding. While this method appears ruthless, it instantly identifies idle resources and forcefully reallocates them to high-growth initiatives.
Balancing the Capital and Operating Budgets
Corporate budgets are generally steered along two primary axes. Both axes serve distinctly different time horizons and objectives.
Operating Budget
This represents the expenses required to keep the company alive on a daily basis. The daily watering of the field, the diesel for the tractor, or the monthly salaries of the employees fall under this category. The operating budget ensures the gears of the current machine keep turning.
Capital Budgeting
This is the budget dedicated to massive, strategic investments aimed at the future. For instance, digging a brand-new, giant water well on the farm or purchasing a multi-million-dollar autonomous tractor are subjects of capital budgeting.
- These projects are exceptionally expensive, and their returns take years to materialize.
- If a company allocates its capital budget to the wrong project (e.g., digging a well in a completely dried-out zone), the Opportunity Cost kicks in. That massive sum of money was effectively stolen from another project that could have been highly profitable. Capital budgeting is the ultimate crossroads that dictates a company's long-term destiny.