Derivative Dynamics and Mathematics of the Ice Sculpture
The value of a financial contract depends not only on its present existence but on how well it can withstand the corrosive power of time and the uncertainty of the future.
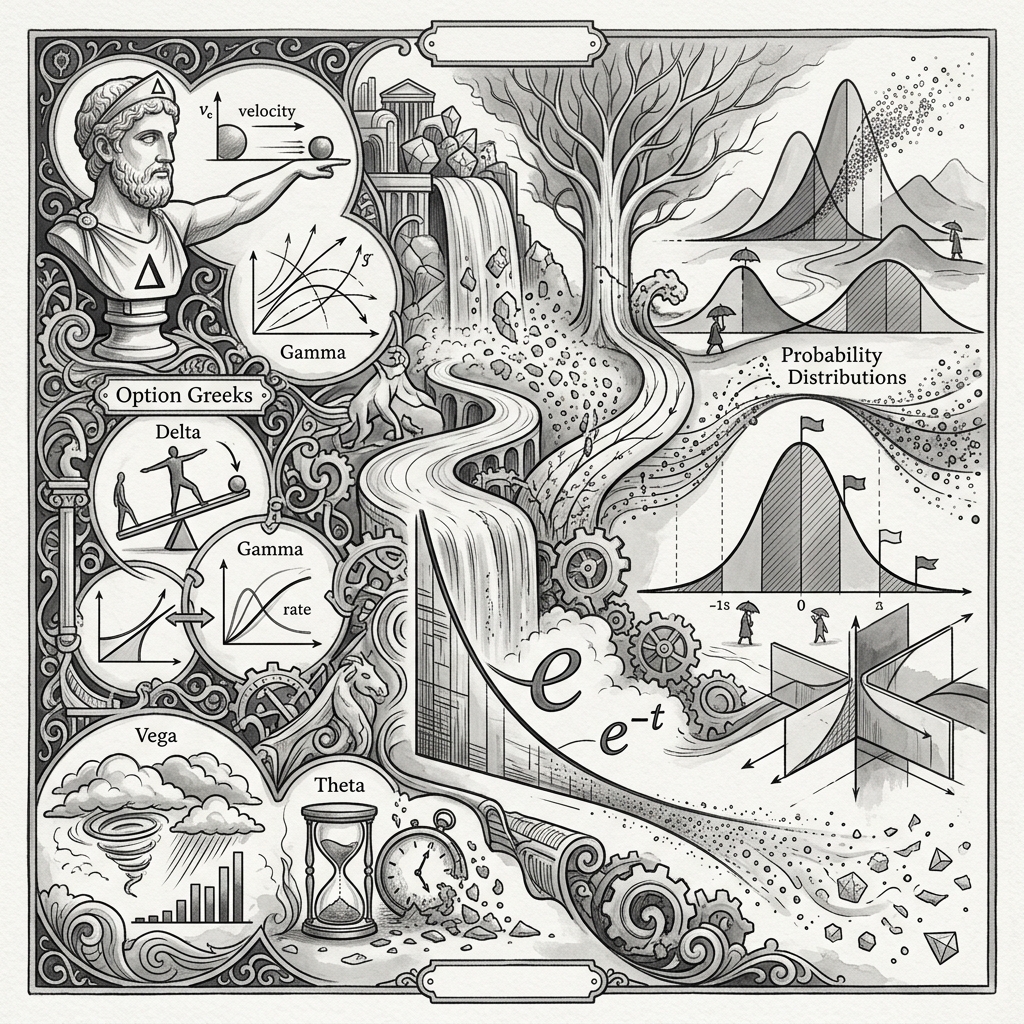
In derivative markets, option contracts are complex financial instruments that give investors the right to buy or sell a specific underlying asset at a predetermined price. However, pricing these contracts, which means determining their premiums, is not a static or simple process. The mathematical sensitivity measures in option pricing, known in the market as the "Greeks," flawlessly model the option premium's journey through time.
Imagine an option contract as a massive ice sculpture. The value of this sculpture (option premium) depends on its own weight, the intensity of the wind in its environment, and the heat of the sun striking it. The Greeks are engineering metrics that calculate exactly how these external factors will melt or reshape the sculpture.
Core Components of Option Pricing
The fundamental factors that determine option premiums are price movement, acceleration, time decay, and market volatility. Let's analyze each of these metrics in structural detail. Investors and financial engineers must masterfully control these four cornerstones to fully manage their portfolio's structural risk.
Delta: Weight and Direction of the Underlying Asset
Delta measures the change in an option's premium resulting from a 1-unit change in the price of the underlying asset. Mathematically, Delta tells the investor how sensitive their position is to the market's direction. If a stock increases by $1 and the option's Delta is 0.50, the option premium will increase by $0.50.Metaphorically, Delta is the pure weight of the ice sculpture. The larger the sculpture (the closer Delta is to 1), the more responsively it moves to tremors on the ground (in the market). Several core mechanics must be considered when analyzing Delta:
- Probability Indicator: Delta is also utilized as a mathematical indicator of the probability that an option will expire in the money.
- Directional Risk: If Delta is positive, you gain when the asset rises, if negative, you gain when it falls.
- Dynamic Change: Delta is not a fixed number, as the asset's price changes, Delta changes accordingly.
Gamma: Price Acceleration and Delta's Sensitivity
Gamma is a second-order derivative that measures how much Delta will change as the underlying asset's price changes. In other words, Gamma is the speed or acceleration of Delta. If there is a sharp and rapid movement in the market, Gamma causes Delta to rise quickly, potentially multiplying the option's value.You can think of Gamma as the slope of the ground where the ice sculpture stands. As the slope increases (as Gamma rises), the sculpture's center of gravity (Delta) shifts rapidly. High Gamma plays a major role in institutional strategies:
- Acceleration Factor: As the price moves in your favor, your position generates profit at a faster rate.
- Risk Multiplier: If the price turns against you, losses grow with the exact same momentum.
- Expiration Effect: As expiration approaches, the Gamma of near-the-money options increases violently, becoming highly explosive.
Theta: The Inevitable Corrosive Power of Time
Theta is the metric that calculates how much an option's premium will depreciate as time passes. Options inherently carry "time value." As expiration approaches, the probability of the price moving in the desired direction decreases, so the contract's time value melts away every day. This phenomenon is known in investment literature as "Time Decay."In our ice sculpture metaphor, Theta is the scorching sun in the sky. No matter how beautiful or solid the sculpture is, as long as the sun (time) shines brightly above, it is doomed to melt (lose value) every single day.
- Exponential Decay: Theta is not linear, the speed of time decay increases drastically as the expiration date nears.
- Buyer vs. Seller: While Theta is an enemy for option buyers, it is a steady profit-generating friend for option sellers (writers).
- Weekend Effect: Because time never stops, Theta continues to operate and consume the premium even when the market is closed.
Vega: The Intensity of Uncertainty and Wind
Vega indicates how much an option's price will change for a 1% change in the implied volatility of the underlying asset. An environment of fear, panic, or extreme expectation in the market increases volatility, this causes option premiums to generally inflate. Even if the price does not change at all, the option contract can become more valuable simply because uncertainty has increased.Vega represents the intensity of the stormy wind blowing around the ice sculpture. The harder the wind blows, the higher the probability that the sculpture will break apart or change shape.
- Fear Premium: Before earnings announcements or geopolitical crises, the market becomes fearful, and Vega skyrockets.
- Price Independence: Even if the underlying asset's price remains static, increased volatility can drive the premium higher.
- Cost of Protection: Market participants are willing to pay higher prices for these sculptures to protect themselves during stormy weather.
Corporate Risk Management and Greek Imbalances
Institutional investors use option Greeks not just to generate profit, but to neutralize their systemic risks entirely. At an institutional level, multi-billion-dollar portfolios cannot be left dependent on a single parameter. Complex strategies like Delta-Neutral allow a portfolio to become completely independent of market direction. In doing so, investors aim to generate consistent returns strictly through market volatility (Vega) or time decay (Theta).