Financial Shields and Forward Contracts
The future is an accumulation of incalculable risks; professionals do not try to predict tomorrow, they buy that uncertainty by placing a lock on the price today.
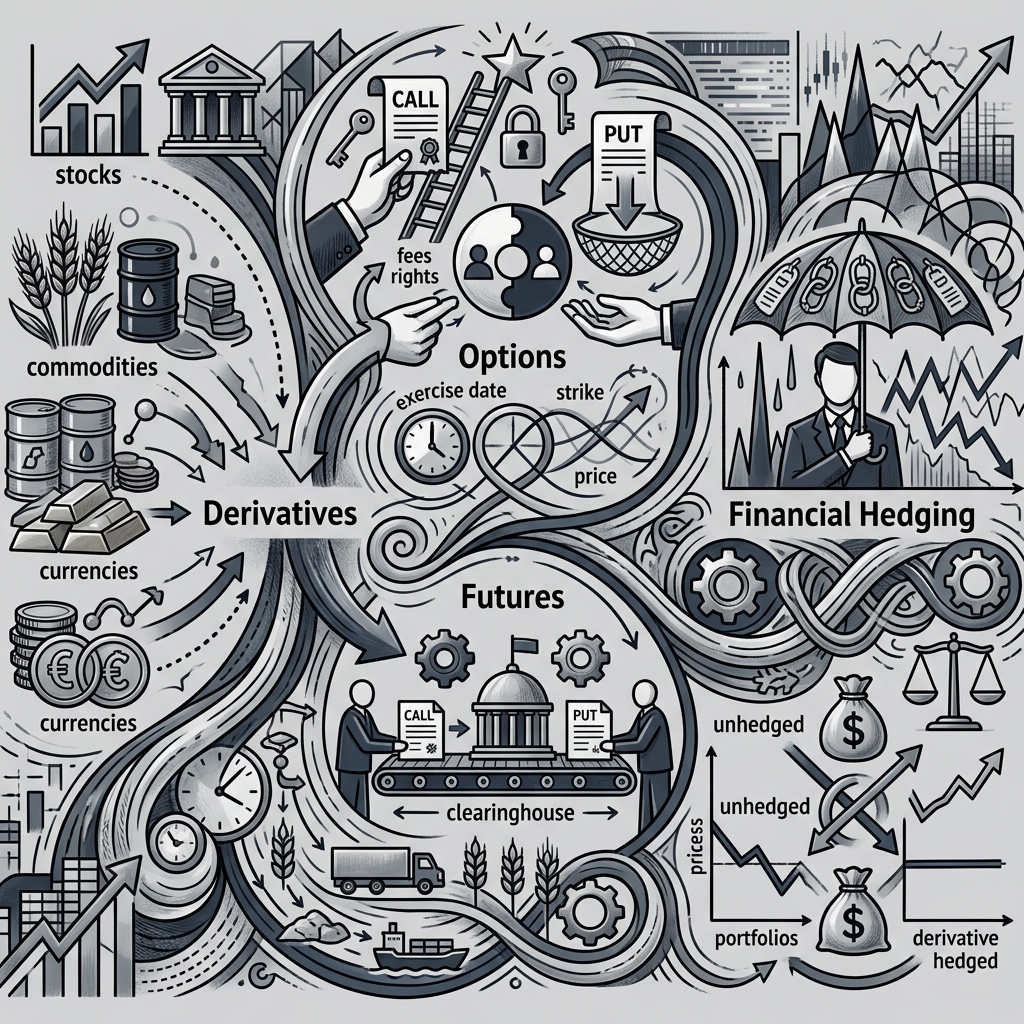
Derivative instruments (Options and Futures) traded in financial markets are advanced financial contracts that have no intrinsic value of their own, but derive their value from an "underlying asset" (gold, oil, stocks, currency). Generally, these instruments are seen by the average person on the street as a gambling tool or high-risk speculation. However, in the real corporate world and institutional finance, these instruments are entirely a financial shield and an insurance policy created for "hedging" purposes. A derivative product allows you to build a wall of guarantee today against future price fluctuations. The biggest difference from purchasing a traditional asset is that the money is not paid today for the asset to change hands tomorrow, but rather the entire contract is written on a forward-looking scenario.
The Underlying Asset and Value Transfer
At the core of derivative contracts lies the underlying asset. The derivative contract itself does not physically produce or store a product, it does not offer a share in company profits like a stock, nor does it pay interest like a bond.
The Mechanics of the Underlying Asset
It is the fundamental reference point that determines how the value of a contract will change. If the contract is based on oil, the price of the contract moves simultaneously with the price of oil in the global markets. Without an underlying asset, a derivative product is no different from an empty piece of paper. The fluctuation of the underlying asset is the sole mathematical engine that directly determines the value of the contract. This requires market analysts to read not only the derivative contract but also the entire production, supply, and demand dynamics of the underlying asset exceptionally well. For example, the value of a wheat futures contract is bound not only to the buyer and seller balance in financial markets but also firmly tied to global rainfall rates, fertilizer prices, and agricultural yields.
Futures and Price Locking
Futures contracts offer price guarantees beyond time, preventing future shocks. In the real world, the vast majority of trade between large producers and consumers is secured in this manner.
The Mechanics of Futures
A Futures contract is a legally binding commitment between two parties to buy and sell a specific asset at a predetermined date in the future and at a fixed price agreed upon today. Think of futures as an agreement made months in advance between a farmer and a baker. The baker locks in the price today to avoid going bankrupt if wheat prices skyrocket. The farmer also locks in their price today to avoid losing money if wheat prices collapse. No matter what the prices are at harvest time, both parties must adhere to the validity of the signature they put down today. This transaction is a zero-sum game where one side profits and the other incurs a loss. When the maturity date arrives in the market, no matter how high or how low the current free market price has gone, the transaction takes place at the locked-in price in the contract. This mechanism provides excellent budget predictability for commercial enterprises.
Options and the Balance of Rights and Obligations
Options work in the exact same way as the logic of insurance, granting you the right to act in exchange for a specific premium. However, unlike futures, they offer unilateral flexibility.
Call Option and Put Option
Options contracts, as the name implies, give the owner an "option," meaning a right, but do not impose an obligation. The party buying the option makes a small upfront payment (Premium) and obtains the right to buy or sell at a specific price in the future. The party selling the option (Writer) collects that premium upfront but is obliged to execute the transaction if the buyer wishes to exercise their right.
- Call Option: This is the right to "buy" at a specific price, purchased by someone who thinks prices will rise or someone who fears that the price of a good they will need in the future will skyrocket. Even if prices in the market go much higher, you can exercise your right to buy cheaply. If the price falls, you throw the contract in the trash and only lose the premium you paid.
- Put Option: This is the right to "sell" at a specific price, purchased by someone who thinks prices will drop or someone who wants to buy insurance against their held asset losing value. If the stock you hold drops by half, you escape the loss by exercising your right to sell at the high price you locked in earlier. If market prices rise, you don't use the option and simply enjoy your stock.
Hedging and the Insurance Function
For large-scale industrial corporations, uncertainty is the biggest enemy of profitability. Even if businesses trust their operational efficiency, raw material crises can lead to bankruptcy.
Corporate Hedging Strategy
In the real business world, derivative instruments are not a tool for speculation or getting rich; they are a strategy to prevent bankruptcy. Derivative instruments are an insurance policy purchased against future uncertainty. Large airline companies lock in the price of oil today using futures contracts against the sudden spike in aviation fuel prices. Thus, they can forecast their fuel costs months in advance and confidently calculate their ticket prices without making a loss. The company chooses not to make extra profit from the price, but merely to ensure price stability and focus on its actual business, which is flight operations. If the oil price drops, the company might seem to have incurred a loss, but its main goal is not to speculate, simply to zero out the risk.